Offshore company formation can make sense when a foreign company solves a real business problem, then survives four checks: home-country tax treatment, banking and payment access, ongoing compliance, and total recurring cost.
Start with the owner’s residence and business model, shortlist jurisdictions only after that, pre-check banking and payment processors, then compare year-one and later-year costs before forming anything.
Our editorial recommendation is to treat incorporation as the last confirmation step, not the first purchase.
A low headline tax rate is useless if the company is taxed where it is managed, cannot open a workable account, or becomes expensive to maintain.
Last fact-checked: October 4, 2026
This guide is for founders, consultants, online businesses, digital nomads, and asset-holding owners considering a company outside their main country of residence or operations.
It covers practical benefits, formation logic, total cost categories, banking, tax and compliance risks, and a pre-incorporation decision process. It is general information, not individual legal or tax advice.
1. What offshore company formation actually means
In this guide, an offshore company is a company formed outside the owner’s main country of residence or day-to-day operations.
The label says where the company is formed, but it does not by itself determine where profits, owners, or management are taxed.
The practical reason to form one is usually operational or structural.
A founder may want better international banking, payment processor access, simpler administration, asset separation, less public exposure, or a tax-efficient structure that remains compliant where the owner lives.
A founder can hold incorporation documents from one country while working, making decisions, signing contracts, and receiving personal income in another.
The company exists in one legal system, while tax and compliance questions can follow the real-world facts.
2. Benefits of offshore company formation
The strongest benefits are conditional.
Offshore company formation is useful when the jurisdiction improves something the business genuinely needs without creating a larger tax, banking, or compliance problem elsewhere.
| Potential benefit | When it has real value | What can cancel it |
|---|---|---|
| Legal tax efficiency | The structure reduces the combined burden while remaining compliant in the owner’s residence | Home-country rules tax the company, owner, or distributed income anyway |
| International banking | The company can receive major currencies and make cross-border payments reliably | Banks reject the owner profile, activity, address, or jurisdiction |
| Payment access | The company can use the processors required by the business model | The intended processor does not support the exact setup |
| Asset separation | Assets or business risks can be held separately from the individual | The structure does not deliver the separation expected for the owner’s situation |
| Administrative flexibility | Formation and routine maintenance can be handled remotely | Banking, substance, or identity checks still require local presence |
| Commercial credibility | Clients and procurement teams accept the company and its banking | The jurisdiction creates extra due diligence or reputational friction |
| Privacy | Public exposure of personal details can be reduced in some structures | Banks, agents, and authorities still require beneficial-owner disclosure |
A software-as-a-service (SaaS) founder who needs a supported payment stack has a different problem from a consultant seeking tax efficiency or an investment owner focused on asset separation.
“Best offshore jurisdiction” is therefore a poor starting question.
3. The pre-incorporation feasibility test
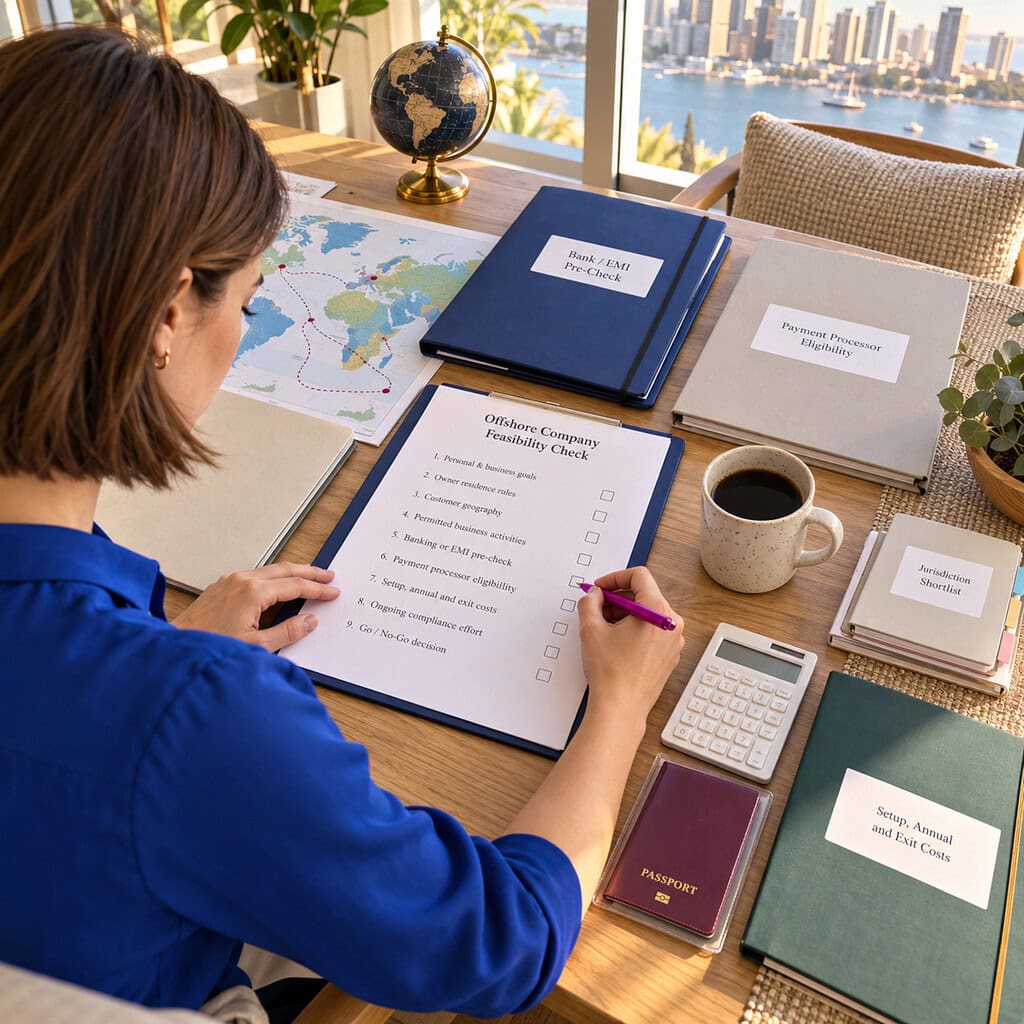
The useful question is whether the structure still works after residence tax, banking, payments, compliance, and recurring cost are included.
Run those checks before choosing a provider or paying a formation fee.
Picture the common failure pattern.
A founder sees a low-tax jurisdiction, pays for incorporation, receives the company documents, and then discovers that the bank wants a real operating address.
Another gets the account but learns that the required payment processor will not support the setup.
Use this sequence:
- Define the exact reason for forming abroad, such as banking, payments, tax efficiency, holding assets, or serving international clients.
- Map the owner’s tax residence, citizenship issues, physical work location, and where management decisions are made.
- Confirm the business model, customer geography, currencies, and payment processors the company must use.
- Shortlist jurisdictions by tax fit, banking, reputation, substance requirements, and maintenance burden.
- Pre-check whether realistic banks or electronic money institutions (EMIs) will accept the owner, activity, address, and jurisdiction.
- Confirm that the intended merchant processors support the structure.
- Model setup, annual maintenance, professional fees, and exit costs.
- Have a qualified cross-border tax professional and lawyer review material tax or legal exposure.
- Form the company only after the structure passes the operational and compliance checks.
A cheap company that cannot bank is just paperwork with renewal fees.
4. Offshore company formation costs
There is no useful universal price for offshore company formation because the headline incorporation fee excludes many costs that decide whether the structure is economical.
Compare total cost of ownership for year one and later years instead.
| Cost layer | What to include |
|---|---|
| Formation | Registry or government charges, formation service, initial documents |
| Local administration | Registered office, registered agent, secretary, or local director where required |
| Accounting | Bookkeeping, accounts, tax returns, annual reporting, audit where applicable |
| Banking | Account opening support, bank or EMI charges, foreign exchange, transfers |
| Payments | Merchant processing and platform-related costs |
| Substance | Office, local management, employees, board activity, or other presence where required |
| Professional advice | Cross-border tax, legal, accounting, and compliance work |
| Travel | In-person bank onboarding or local administration when remote setup is unavailable |
| Renewal | Government renewals and recurring provider fees |
| Exit | Dissolution, final accounts, final filings, certificates, and account closure |
Build a year-one figure and a normal annual figure.
Then ask whether the expected tax or operational benefit clearly exceeds those costs and the administrative burden.
The cheapest jurisdiction can be the most expensive mistake if it later needs extra substance, specialist filings, or a new banking solution.
5. Tax and compliance risks
The largest risks come from the interaction between the owner’s real life and the company’s legal address.
A foreign registration does not erase rules in the countries where the owner lives, works, manages the company, or earns income.
Key concepts include controlled foreign corporation (CFC) rules, permanent establishment (PE), and management-and-control tests.
The exact treatment depends on the countries involved, so identify which jurisdictions may tax or regulate the company or owner before formation.
Ongoing obligations can remain even when the company has little or no revenue.
Depending on the jurisdiction and structure, the owner may still face annual returns, bookkeeping, tax filings, beneficial-owner reporting, or renewal requirements.
Zero sales do not automatically mean zero compliance.
Economic substance creates another risk.
Some structures may need more than a registered address when tax residence, banking, or local rules depend on where real management and activity occur.
A virtual office can satisfy one administrative requirement while failing a bank’s onboarding standard or the intended tax position.
6. Banking and payment processing risks
Banking should be tested before incorporation because a valid company is not automatically a bankable company.
Banks and EMIs assess beneficial owners, residence, business activity, expected transactions, source of funds, address, and jurisdiction through know-your-customer (KYC) checks.
The painful version is easy to picture: the incorporation provider has finished its job, but the founder is still emailing banks, uploading address documents, explaining the business model, and discovering that the registered-agent address is not enough.
Payment processing can be equally decisive.
For SaaS, e-commerce, and online services, access to Stripe, PayPal, or another merchant processor may matter more than a small difference in tax rate.
Verify support for the exact company, owner, bank setup, and activity before paying to form it.
Also plan for resilience. A structure that depends on one bank or one processor has an obvious single point of failure.
7. How to choose an offshore jurisdiction
Choose an offshore jurisdiction by fit with the owner’s residence and the business’s operating needs, not by a ranking of nominal tax rates.
The shortlist should survive tax, banking, payment, substance, reputation, compliance, and cost checks.
| Decision area | What to verify before choosing |
|---|---|
| Owner context | Tax residence, citizenship, physical work location, expected moves |
| Business model | Consulting, SaaS, e-commerce, holding, investing, crypto, or another activity |
| Tax interaction | Company residence, CFC exposure, PE risk, management and control, owner extraction |
| Banking | Account availability for this owner and activity, remote versus in-person onboarding |
| Payments | Support from the processors the business actually needs |
| Substance | Local director, office, staff, management, or other presence |
| Compliance | Returns, bookkeeping, tax filings, audit, beneficial-owner requirements |
| Reputation | Acceptance by customers, banks, processors, and counterparties |
| Cost | Setup, annual maintenance, advice, banking, substance, travel, and exit |
| Exit | Dissolution process, final reporting, and remaining fees |
The British Virgin Islands, Cayman Islands, Seychelles, United Arab Emirates, Hong Kong, and Singapore appear frequently in offshore comparisons.
That does not make any one of them the default choice. The owner’s facts and the business’s banking and payment needs can reverse the answer.
8. Common myths and failure modes
Offshore formation attracts simple claims because simple claims fit neatly on a sales page. The actual structure is less cooperative.
| Myth | What actually happens |
|---|---|
| “A 0% corporate tax rate means I pay no tax.” | The owner’s residence, company residence, management, CFC rules, PE, and distributions can change the result. |
| “Once the company exists, the bank account is straightforward.” | Banking has its own KYC, address, activity, and owner checks. |
| “Privacy means anonymity.” | Public visibility and disclosure to banks, agents, and authorities are different things. |
| “The formation fee is the real cost.” | Annual administration, accounting, banking, substance, advice, and exit can matter more. |
| “A dormant company has nothing to do.” | Zero activity can still leave filing, renewal, or reporting obligations. |
| “Remote formation means everything stays remote.” | Banking or substance needs may still create travel or local-presence requirements. |
Provider selection deserves the same skepticism.
Ask what the provider handles after incorporation, what costs extra, who is responsible for banking and compliance, and what happens if the proposed bank or processor rejects the application.
9. A practical go or no-go plan
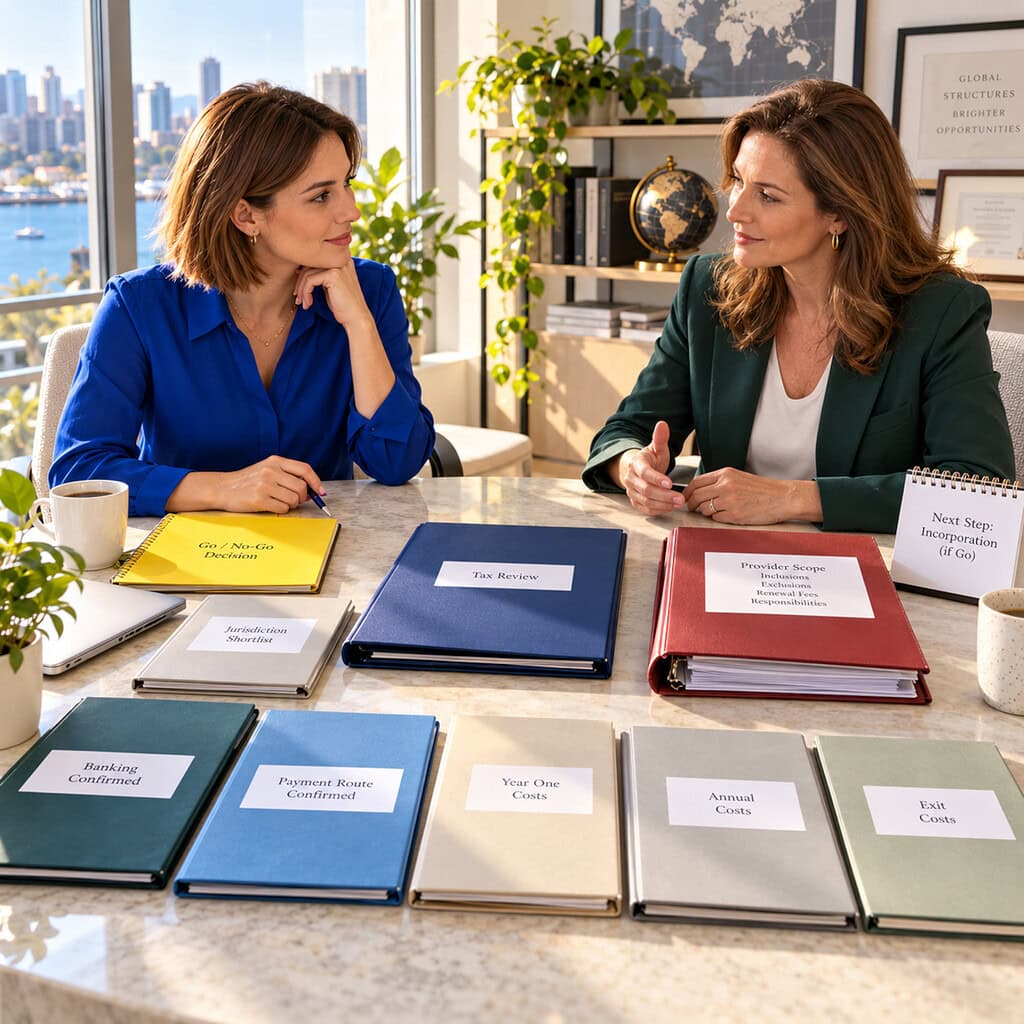
A workable offshore company should pass the checks in the same order the business will depend on them.
Do not let the formation certificate become the expensive part of your due diligence.
Before paying a provider:
- Write down the business outcome the foreign company must deliver.
- Get the owner’s cross-border tax position reviewed.
- Shortlist jurisdictions that fit the business activity.
- Confirm at least one realistic banking route.
- Confirm the required payment processor or acquiring route.
- Identify substance and ongoing filing obligations.
- Build year-one, annual, and exit cost estimates.
- Obtain a written provider scope showing inclusions, exclusions, renewal fees, and responsibilities.
- Decide whether the net benefit still justifies the cost and complexity.
If any core dependency remains a guess, the structure is not ready to buy.
FAQ
Is offshore company formation legal?
It can be legal, but compliance depends on the countries connected to the owner, management, business activity, and income. See Sections 3 and 5.
Does an offshore company mean zero tax?
No. A low or zero corporate rate in the formation jurisdiction does not settle taxation in the owner’s residence or place of management.
See Section 5.
How much does offshore company formation cost?
It depends on the jurisdiction and operating requirements.
Compare formation, annual administration, accounting, banking, substance, professional advice, and exit costs in Section 4.
Can an offshore company open a bank account remotely?
Sometimes, but remote incorporation does not guarantee remote banking.
Bank policy, owner residence, address evidence, and business activity can still require more documentation or an in-person step. See Section 6.
Can I use Stripe or PayPal with an offshore company?
It depends on the exact company, owner, bank, business model, and processor eligibility.
Verify the payment stack before incorporation as described in Sections 3 and 6.
Do I need economic substance?
It depends on the jurisdiction, activity, tax position, and banking requirements.
Identify the actual office, management, director, or staffing requirements before comparing costs. See Sections 5 and 7.
Is an offshore company worth it for a small business?
Only when the operational or tax benefit clearly exceeds the recurring cost, compliance burden, and failure risk.
Use the go or no-go process in Section 9.
What happens if I later move to another country?
The structure may need reassessment because a new tax residence can change how the company and owner are treated. See Sections 3 and 7.
Conclusion
Offshore company formation is worth considering only after the structure still works when residence tax, banking, payments, compliance, and recurring cost are included.
The paperwork is usually the easy part. The real decision is whether the company remains usable and defensible after incorporation.
1. Verify the owner’s tax position before choosing the jurisdiction.
2. Confirm banking and payment access before paying formation fees.
3. Compare total annual cost and exit cost, not the advertised setup price.
Further reading
- Offshore Company Formation: What You Need to Know: A broad overview of formation, banking, compliance, and ongoing costs.
- Best Offshore Company Jurisdictions: A jurisdiction comparison covering cost, banking, setup, and suitability.
- Offshore Company Formation Costs: A closer look at registry charges, service fees, and recurring cost layers.
- Company Formation: A commercial formation overview with jurisdiction and service considerations.
- Best Offshore Company Jurisdictions: A comparison focused on business purpose, banking, reporting, and maintenance.
- Offshore Companies: A general overview of offshore-company advantages and disadvantages.
- Internal Revenue Service: Official US tax information for owners with US tax obligations.
- Financial Crimes Enforcement Network: Official US information on financial transparency and compliance topics.