To cut business costs without hurting growth, diagnose the financial problem, map each expense to the business outcome it supports, and remove unused or duplicated spend first.
Then renegotiate necessary costs, simplify inefficient workflows, improve pricing or terms where the economics are weak, and cut productive capacity only if the remaining gap still requires it.
The core rule is simple: cut waste before capability.
A lower expense total is useless if sales, quality, delivery, retention, or owner capacity deteriorate faster than the savings arrive.
Our recommendation is to start with reversible changes and define a damage threshold before making any structural cut.
Last fact-checked: October 4, 2026
This guide is for US owners and managers trying to improve profitability, cash flow, or runway without blindly shrinking the business.
It covers expense diagnosis, software, suppliers, payroll, marketing, inventory, outsourcing, pricing, working capital, and rollback metrics.
Recommendations are editorial judgments, not guarantees of a particular financial result.
1. Diagnose the financial problem
Cutting business costs safely starts with identifying the problem you are actually trying to solve.
A company with weak margins needs different action from a profitable company that is short of cash because customers pay late or inventory absorbs working capital.
Four problems commonly get lumped together as “costs are too high.”
| Problem | What it looks like | First place to investigate |
|---|---|---|
| Profitability problem | Revenue exists, but gross or operating margin is weak | Pricing, product mix, customer profitability, supplier economics |
| Cash-flow problem | The business can be profitable on paper but struggles to meet payments | Receivables, deposits, supplier terms, inventory timing |
| Burn and runway problem | Monthly cash outflow is too high for the available cash balance | Speed and cash impact of reductions, not only annual savings |
| Efficiency problem | The business is healthy but carries unnecessary friction or waste | Recurring spend, utilization, workflow complexity, vendor terms |
A business doing more revenue and making less profit should resist the reflex to celebrate the top line and slash whatever invoice looks irritating.
One ecommerce owner described monthly revenue of about $90,000 after expansion, yet profit had disappeared.
The useful question was where the economics had deteriorated, not whether sales were growing.
Use this sequence for the full review. The order matters because each stage reduces the chance of damaging something the next stage depends on.
| Stage | Decision | Move forward when |
|---|---|---|
| 1 | Diagnose the financial problem | You know whether the pressure is profit, cash flow, burn, or efficiency |
| 2 | Protect productive capacity | You can identify costs that create or protect revenue, service, quality, or throughput |
| 3 | Build the cost map | Recurring and irregular spending is visible from actual transactions |
| 4 | Remove low-risk waste | Unused, duplicated, stale, or clearly non-performing spend has been addressed |
| 5 | Improve utilization and simplify | Necessary tools, processes, and assets are being used efficiently |
| 6 | Renegotiate costs and terms | Valuable capabilities have been competitively priced before cancellation |
| 7 | Automate or outsource selectively | The total workflow becomes cheaper or frees higher-value capacity |
| 8 | Review payroll and service capacity | Any labor change has been tested against throughput and customer impact |
| 9 | Review marketing economics | Channels are judged by customer economics, not by how discretionary they look |
| 10 | Optimize inventory and working capital | Cash is released without creating avoidable stockouts or service failures |
| 11 | Fix pricing and complexity | Margin leaks from underpricing, poor customer mix, or unnecessary offers are addressed |
| 12 | Pilot and measure structural changes | Guardrails and rollback triggers exist before hard-to-reverse cuts |
If survival is the issue, timing changes the order inside each stage.
A saving that pays back in 18 months can be sensible for a stable company and irrelevant to a company with only a few months of runway.
If the business is close to running out of cash, have a certified public accountant (CPA) or qualified financial adviser review decisions that materially affect solvency, taxes, or financing.
2. Cut waste before capability
The safest cost-cutting principle is to cut waste before capability.
A cost is waste when removing it does not materially weaken the business’s ability to acquire customers, serve them, deliver quality, maintain throughput, or free valuable management time.
The hard part is that the same category can sit on either side of the line. Software can be unused clutter or a productivity engine.
Payroll can be excess capacity or the bottleneck preventing more sales. Inventory can be dead stock or the stock required to keep promises.
A practical classification is more useful than a simple keep-or-cut decision.
| Decision | Use it when | Growth risk |
|---|---|---|
| Cut | Usage and value are low, and removal does not impair a needed capability | Lower |
| Renegotiate | The capability matters, but the price or contract terms are weak | Lower |
| Replace | The function is necessary, but the provider or tool is inefficient | Medium |
| Redesign | The cost exists because the workflow is fragmented or poorly designed | Medium |
| Protect or invest | The cost clearly enables profitable demand, capacity, retention, or owner leverage | Higher if reduced |
Before touching a meaningful expense, run a short decision test.
- What business outcome does this expense enable?
- What stops, slows, or degrades if it disappears tomorrow?
- Does it create revenue, protect revenue, save expensive labor, reduce risk, or add capacity?
- Is the asset or service actually being used enough to justify its cost?
- Can the same outcome be produced more cheaply without adding hidden work?
- Can the price or contract be renegotiated before the capability is removed?
- Does another expense duplicate the same function?
- Will cutting it shift work onto the owner or another overloaded employee?
- Which customer, quality, delivery, or sales metric might worsen afterward?
- What result would make you reverse the decision?
A cheaper line item can make a more expensive business.
That happens when the saving is visible immediately but the replacement cost appears later as lost time, errors, churn, delays, or weaker sales.
3. Build a complete cost map from actual transactions
A reliable business cost review starts with real transaction history, not a spreadsheet reconstructed from memory.
Recurring charges are especially easy to miss when different employees own different tools, cards, vendors, and renewal dates.
Pull the profit and loss statement, bank transactions, card statements, software billing records, lease obligations, vendor invoices, and payroll costs for a meaningful review period.
Then assign every material expense an owner and an economic function.
Use these categories to make the review operational:
- Revenue creation, such as sales staff or proven acquisition.
- Revenue protection, such as customer support or quality control.
- Production and delivery capacity, such as labor, fulfillment, or critical systems.
- Risk control, such as insurance or required compliance work.
- Time leverage, such as software or outsourced administration that frees expensive staff.
- Waste or uncertainty, where usage, ownership, or business value is unclear.
Software deserves special treatment because small purchases accumulate quietly.
One 12-person company reported paying for 23 software products at a combined $4,100 per month. The problem was not one outrageous contract.
It was a stack of individually defensible purchases that had stopped being managed as a portfolio.
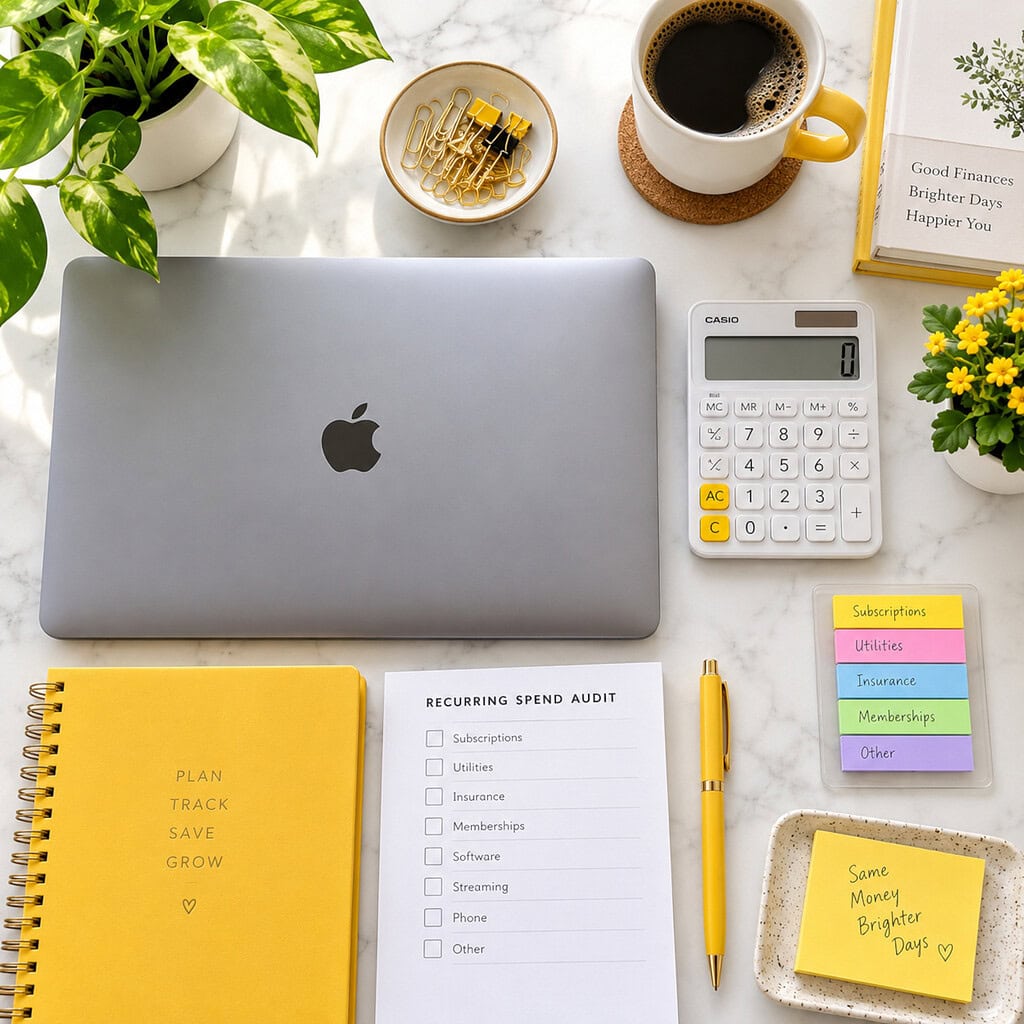
Run this recurring-spend audit from payment history rather than a manually maintained subscription list.
- Export recurring charges from bank accounts and company cards.
- Add annual renewals that do not appear in the latest month.
- Assign one accountable owner to every tool or service.
- Check actual use over the last 30, 60, and 90 days where usage data exists.
- Identify unused seats, premium tiers, add-ons, and duplicate functions.
- Record the renewal or cancellation date for every material contract.
- Write down the workflow that would break if each item disappeared.
- Flag anything with no clear owner, recent use, or measurable function for review.
This is also where owner time belongs.
Bookkeeping, invoicing, website maintenance, scheduling, content, and fulfillment may feel “free” when the owner does them personally.
They are not free if those hours replace sales, product work, customer relationships, or management.
4. Remove low-risk waste first
Low-risk cost reductions are expenses where the business can save money without materially shrinking productive capacity.
These should usually be exhausted before major staffing, service, or growth cuts enter the discussion.
Common first targets include the following.
| Cost area | What to look for | Safer action |
|---|---|---|
| Software | Unused seats, overlapping tools, unnecessary tiers, dormant add-ons | Cancel, downgrade, or consolidate |
| Services | Stale retainers, unused subscriptions, automatic renewals | Cancel or renegotiate |
| Projects | Features or initiatives with no validated customer value | Pause or stop |
| Inventory | Slow or dead stock that ties up cash | Reduce reorders, clear obsolete stock |
| Office capacity | Space or services no longer used enough | Right-size at renewal where practical |
| Fees | Payment, telecom, shipping, banking, or service charges that have not been shopped | Compare providers and renegotiate |
| Administration | Duplicate data entry and reconciliation | Simplify the process before adding another tool |
A small saving is still worth taking when it is genuinely low-risk, but many tiny savings will not solve a large structural deficit.
If monthly burn needs to fall sharply, canceling forgotten subscriptions is housekeeping, not a rescue plan.
The right sequence is to clear obvious waste, total the savings, and then measure the remaining gap.
That prevents a company from making a painful structural cut for an amount that could have been found elsewhere.
One owner reviewing recurring costs found unnecessary add-ons in a reviews software package and reported saving about 1,200 British pounds per year by downgrading.
Treat that as an individual result, not a target.
The lesson is that automatic renewals turn yesterday’s choices into today’s overhead unless someone is required to revisit them.
5. Improve utilization and simplify workflows
Necessary business costs should be improved before they are removed.
Poor utilization, fragmented systems, duplicate processes, and manual reconciliation can make a useful capability look more expensive than it really is.
Software is the cleanest example.
Replacing a paid tool with a cheaper one can backfire if employees spend more time rebuilding reports, moving data, correcting inconsistencies, or switching between systems.
A lower subscription price is only a saving if the workflow stays economically cheaper.
Use total workflow cost rather than subscription price alone:
Net economic saving = direct cost reduction - added operating cost - lost gross profit caused by the change
The last term can be zero if the change does not affect sales, retention, quality, or capacity.
Do not assume it is zero before the change has been observed.
Worked example
The following numbers are illustrative, not a benchmark.
Suppose a replacement reduces software spend by $700 per month but adds 12 hours of staff work at an illustrative loaded cost of $30 per hour.
| Item | Illustrative monthly amount |
|---|---|
| Direct software saving | $700 |
| Added staff cost | $360 |
| Lost gross profit | $0 in the initial test |
| Net economic saving | $340 |
The calculation is $700 - $360 - $0 = $340 per month. The change still saves money, but less than half the invoice reduction suggests.
For the stress test, assume the direct software saving is only half the estimate while the added labor remains the same.
The calculation becomes $350 - $360 - $0 = -$10. The “cheaper” system now costs more before any customer impact is counted.
The same logic applies to office space, equipment, vehicles, agencies, and outsourced functions.
First ask whether the resource is underused because it is unnecessary or because the surrounding process is broken.
A practical simplification review should look for duplicate approvals, repeated data entry, custom exceptions, unnecessary service tiers, and tools that exist only to reconcile other tools.
Sometimes the best cost cut is removing complexity rather than replacing one invoice with another.
6. Renegotiate necessary costs and payment terms
Renegotiation can lower business costs without removing the capability the company still needs.
That makes suppliers, software contracts, insurance, leases, logistics, professional services, and payment terms attractive targets before outright cancellation.
Start by separating supplier value from supplier price.
A strategic vendor that delivers reliably, fixes problems quickly, and gives favorable terms should not be compared with a cheaper quote as if both offers were identical.
Use this negotiation checklist before renewal.
- Pull the current contract, renewal date, notice period, and termination terms.
- Compare current pricing with credible alternatives for the same service level.
- Identify unused features, volume tiers, or bundled services you do not need.
- Ask for pricing at your actual usage rather than the original forecast.
- Negotiate payment timing, minimum commitments, and renewal length alongside price.
- Calculate switching costs, including migration, downtime, training, and service risk.
- Protect any service level, response time, or quality term that matters operationally.
- Put the final economics in writing before signing a longer commitment.
A commercial tenant in one owner discussion reported negotiating monthly rent from $9,200 to $8,000 plus three free months.
Another owner reported cutting insurance cost by roughly 35% after shopping providers.
Neither result is a general promise. Both show why automatic renewal deserves scrutiny.
Payment terms matter even when accounting expense stays the same.
Faster deposits from customers, milestone billing, tighter collection, supplier credit, and better purchase timing can reduce the cash the business must finance.
Be careful with aggressive negotiation that weakens a valuable relationship.
A supplier can recover a headline discount through slower service, worse terms, lower priority, or stricter commitments.
Price is one contract term among several.
7. Automate and outsource only when total economics improve
Automation and outsourcing reduce costs safely when they remove repetitive work, convert unnecessary fixed cost into variable cost, or free valuable people for higher-value tasks.
They fail when the direct price falls but quality, management burden, or customer experience deteriorates.
Good automation candidates are predictable, repetitive workflows with clear rules.
Invoice routing, reminders, scheduling, routine reporting, data entry, and simple support requests often fit that description.
Complex exceptions and high-empathy customer issues usually need more judgment.
Outsourcing should be judged by cost per useful outcome, not by the hourly rate.
A low-cost provider that creates rework, missed deadlines, or constant supervision can be more expensive than an employee who costs more on paper.
One fulfillment discussion captured the trade-off clearly.
Outsourcing could increase direct fulfillment cost and still improve the business if it released the owner from packing work and created more time for sales and growth.
Spending more on one line can reduce the total economic cost of running the company.
Use this test before automating or outsourcing a workflow.
- Define the output you need, including quality and turnaround time.
- Measure the current hours and direct costs required to produce that output.
- Identify which tasks are repetitive and which require judgment.
- Estimate transition, training, integration, and management effort.
- Decide where exceptions will go when the automated or outsourced process fails.
- Track rework, complaints, cycle time, and staff time after the change.
- Compare the full before-and-after workflow cost after a trial period.
Owner time deserves particular attention.
If the owner is doing payroll, invoicing, scheduling, and fulfillment to avoid spending money, the company may be saving cash while starving the activities only the owner can perform.
8. Protect payroll and customer service capacity
Payroll cuts require a higher burden of proof because employees often represent the company’s ability to sell, produce, deliver, support customers, and recover from problems.
The largest line item is not automatically the largest source of waste.
Before reducing a role, separate unused capacity from hidden bottlenecks.
An employee can look underutilized because demand is weak, because the workflow is broken, or because their value appears indirectly through faster delivery and fewer errors.
One manufacturing owner described a damaging loop: insufficient cash prevented hiring, insufficient staffing limited production, and limited production prevented the business from serving available demand.
The owner also lost time for sales and marketing because operations consumed the day.
Use a headcount review that follows the work, not only the salary line.
- What revenue does the role directly or indirectly enable?
- Which customers, workflows, or deadlines depend on the role?
- What happens to throughput if the role disappears?
- Who absorbs the work, and do they have capacity to absorb it?
- Does the workload vanish, or does it move to a more expensive person?
- Will the cut create overtime, errors, slower service, or owner overload?
- Could hours, scheduling, process design, or variable staffing solve the problem first?
- How hard and expensive would the capability be to rebuild later?
Customer support deserves the same discipline.
Cutting service cost by forcing shorter interactions can create repeat contacts, refunds, churn, and negative reviews if the actual problem remains unresolved.
Cost per resolved problem is more useful than cost per contact.
Savings that destroy capacity are debt with a delayed invoice.
If a payroll cut is necessary for survival, define exactly which output will decline and what level of decline the business can tolerate.
9. Cut marketing by unit economics rather than by budget
Marketing should be reduced when a channel fails to produce acceptable customer economics, not simply because the expense looks discretionary.
Proven acquisition can be growth infrastructure, while unmeasured or non-performing campaigns can be waste.
Review marketing at the channel and campaign level.
Cost per acquired customer, gross profit from acquired customers, payback period, conversion quality, retention, and downstream revenue matter more than the total marketing budget alone.
A company with high churn can easily make the wrong move in either direction.
Increasing acquisition sends more customers into a leaky system, while cutting every campaign can weaken future pipeline without fixing the retention problem.
Use a channel review before reducing spend.
- Measure customer acquisition cost for each meaningful channel.
- Estimate the gross profit those customers produce over the relevant relationship period.
- Separate channels with measurable demand capture from longer-term brand activity.
- Identify campaigns that produce traffic or leads but little downstream activity.
- Check whether customer quality differs materially by channel.
- Look for retention, onboarding, payment failure, or service problems after acquisition.
- Set a review window long enough to capture the normal lag between spend and sales.
That lag matters.
A marketing cut can look successful for the first month because the invoice disappears immediately while the sales pipeline is still consuming leads generated earlier.
The damage may show up 30, 60, or 90 days later.
Do not protect a campaign merely because “marketing is essential.”
Protect the channels with defensible economics, and challenge the rest like any other expense.
10. Optimize inventory and working capital without starving demand
Inventory cost reduction should release cash without creating avoidable stockouts, delayed delivery, or lost sales.
The target is the lowest working-capital commitment that still supports the service level customers actually need.
Too much inventory traps cash, increases storage, and raises obsolescence risk.
Too little inventory moves the problem from the balance sheet to the customer experience.
Review inventory by sales velocity, lead time, margin, supplier reliability, stockout cost, minimum order quantity, cash tied up, and obsolescence risk.
Slow, expensive inventory deserves more attention than a low-cost item that turns quickly.
A practical inventory review should start with aging rather than intuition.
Identify the last sale or order date for each material item, the capital tied up, and whether the item supports a strategic customer or product line.
Working-capital pressure also comes from timing outside inventory.
A viable business can run short of cash because payroll happens before customers pay, suppliers require cash before production, or a large contract demands raw materials before final payment.
A food manufacturer described demand and a significant upcoming contract but lacked enough cash to buy raw materials.
The useful remedies included supplier terms, deposits, and payment structure, not only spending cuts.
That distinction matters because cost reduction and cash release are different levers.
Negotiating a deposit does not reduce accounting expense, but it can reduce the amount of outside cash needed to fulfill the order.
11. Fix pricing customer mix and product complexity
Some businesses do not have an expense problem.
They have an underpricing, customer-mix, product-mix, or complexity problem that cost cuts alone will not repair.
Start with contribution economics.
If a product, service, or customer produces revenue but consumes excessive labor, support, customization, inventory, or management time, revenue growth can conceal deteriorating profitability.
Individual owner experiences show why pricing deserves a place in the review.
One service business owner reported raising prices by 30% and losing only four of 61 customers.
Another reported a 25% increase with no cancellations. Those outcomes are anecdotes, not evidence that similar increases are safe for another company.
The useful lesson is that owners can overestimate price sensitivity and tolerate weak margins longer than they should.
Test the economics before assuming the only available lever is cost reduction.
Customer profitability matters for the same reason.
A high-revenue account can still be unattractive if it requires constant exceptions, late collections, custom work, or disproportionate support.
Product and service complexity can create a quieter version of the same problem.
Every extra SKU, custom option, service tier, supplier, exception, and workflow adds coordination work.
The expense may appear in labor, inventory, software, or mistakes rather than under a line called “complexity.”
Use this review when the business is busy but margins remain weak.
- Calculate gross or contribution profit by product, service, or customer segment where the records allow it.
- Identify accounts with unusually high support, customization, collection, or delivery burden.
- Identify low-volume products that require separate inventory, suppliers, or workflows.
- Check whether minimum project size, service scope, or support boundaries are too loose.
- Model whether price changes or simpler offers improve margin more safely than cutting capacity.
- Stop speculative work that consumes resources without validated customer value.
A project can be “growth” in a planning deck and still be waste in the operating business.
New features, locations, or offers need the same economic discipline as old expenses.
12. Pilot changes measure damage and make structural cuts last
The safest cost reductions are reversible, measurable, and tied to a rollback trigger.
Structural cuts such as layoffs, major supplier changes, site closures, or removal of proven acquisition capacity deserve stronger evidence because they are harder to undo.
Prefer tests that can be reversed cheaply.
Downgrade unused software, renegotiate a contract, pause a weak experiment, reduce an inventory order, trial outsourcing, or remove a duplicate process before destroying a capability that will be expensive to rebuild.
Every material cut should have two numbers: a savings target and a damage threshold.
The first tells you whether the cut worked financially. The second tells you when the business is paying too much elsewhere for that saving.
| Area being changed | Possible guardrail | Possible rollback signal |
|---|---|---|
| Marketing | Pipeline, conversion, acquisition quality | Sustained deterioration beyond the agreed threshold |
| Customer service | Resolution time, repeat contacts, churn | Service deterioration that erases the saving |
| Staffing | Throughput, backlog, overtime, delivery time | Capacity or quality falls beyond the planned limit |
| Supplier | Defects, lead time, reliability | Hidden operating cost exceeds the price saving |
| Software | Staff hours, error rate, workflow time | Manual work recreates the removed cost |
| Inventory | Stockouts, fill rate, lost orders | Service level falls below the required standard |
When a large structural gap remains after the safer stages, major cuts may still be necessary.
At that point the decision should be explicit: which capability is being reduced, what output will fall, how much cash is saved, and how the business will operate with the smaller capacity.
A 30-day cost-cutting plan
- In the first week, classify the problem as profitability, cash flow, burn, or general efficiency.
- Export the full cost base from accounting, banking, cards, payroll, and recurring billing.
- Assign each material cost to revenue, protection, capacity, risk, time leverage, or unclear value.
- Remove unused subscriptions, duplicate tools, stale services, and obviously non-performing work.
- Renegotiate material vendors, insurance, software, logistics, and contract terms before replacing them.
- Review payroll, marketing, inventory, and customer economics with the operational metrics attached.
- Pilot reversible workflow, automation, outsourcing, pricing, or assortment changes where the economics support them.
- At day 30, compare realized savings with guardrail metrics and reverse changes that are creating larger downstream losses.
Common cost-cutting myths
| Myth | What actually happens |
|---|---|
| The biggest expense should be cut first | Large costs often represent the largest productive capabilities, so size alone is a poor test |
| Free software is always cheaper | A free tool can cost more if employees recreate missing functionality manually |
| Marketing is either sacred or wasteful | Each channel should be judged by customer economics and timing |
| Outsourcing saves money because labor is cheaper | Direct cost can rise while total economics improve, or quality and management cost can erase the saving |
| Less inventory is always better | Lower stock frees cash until stockouts, delays, or lost sales become more expensive |
| Revenue growth proves the business is healthy | Revenue can rise while margin, cash flow, or customer economics deteriorate |
Structural cuts are sometimes unavoidable.
They should be the last step in a disciplined process, not the first reaction to a frightening monthly report.
FAQ
What business expenses should I cut first?
Start with unused, duplicated, stale, or clearly non-performing expenses that can be removed without weakening productive capacity.
Section 4 covers the lower-risk categories and the order for reviewing them.
Should I cut staff if payroll is my largest expense?
It depends on whether payroll is excess capacity or the capability that creates throughput, sales, service, or quality.
Section 8 gives a headcount test before any role is removed.
Should I cut marketing when cash flow is tight?
Cut channels with weak customer economics before cutting proven acquisition across the board.
Section 9 explains how to review acquisition cost, customer quality, payback, and delayed pipeline effects.
How can I reduce software costs without creating more work?
Measure the total workflow cost before and after any cancellation, downgrade, or replacement.
Sections 3 and 5 cover usage audits, overlap, added labor, and a worked example.
Is renegotiating suppliers better than switching vendors?
Often, yes, when the supplier is reliable and the capability is still valuable.
Section 6 explains how to compare price, terms, service level, and switching cost before moving.
Can outsourcing reduce costs without layoffs?
Yes, if it converts the right fixed work into variable cost or frees higher-value capacity without creating quality or management problems.
Section 7 gives the test for deciding whether outsourcing actually improves total economics.
How do I know if a cost cut is hurting growth?
Track a guardrail metric that reflects the capability being changed, such as pipeline, churn, throughput, defects, delivery time, or stockouts.
Section 12 shows how to pair savings targets with rollback signals.
How often should I review business expenses?
There is no universal interval in the evidence used here, but renewals and recurring charges should have an accountable owner and a defined review point.
Section 3 shows how to build that review into the cost map.
Conclusion
The safest principle is still to cut waste before capability.
Diagnose the real problem, remove low-risk waste, improve utilization, renegotiate, simplify, and test reversible changes before reducing the people or systems that make profitable growth possible.
1. Protect the mechanism that makes money.
Tie every major cost to revenue, service, quality, capacity, risk, or owner time before deciding what to remove.
2. Demand a real economic saving.
Count added labor, switching cost, customer impact, and working-capital effects rather than celebrating the smaller invoice.
3. Make hard cuts measurable and reversible where possible.
Set a savings target, a guardrail metric, and a rollback trigger before the change goes live.
Further reading
- U.S. Small Business Administration: Federal business resources on planning, finance, operations, and managing a small company.
- Internal Revenue Service: Official federal tax information for businesses, including record-keeping and tax obligations.
- Xero business cost saving ideas: A broad practical overview of expense audits, suppliers, inventory, outsourcing, and cost reduction.
- Sage guide to reducing business costs: Practical coverage of quick savings, structural changes, cash flow, staffing, and marketing decisions.
- Capital One guide to decreasing operating costs: An explanation of operating-cost categories and how to audit fixed and variable expenses.
- Shopify guide to reducing business costs: Growth-oriented ideas covering acquisition, teams, suppliers, automation, and ecommerce operations.
- Kudwa guide to cutting costs without hurting growth: A strategic approach to contribution economics, downstream effects, pilots, and rollback triggers.
- Business owners discussing recurring cost cuts: Practitioner discussion of subscriptions, insurance, vendor reviews, and the risk of cutting productive capacity.
- Flying Solo cash-flow discussion: A practitioner example of how staffing, production, sales capacity, supplier terms, and cash flow can interact.