To start a cooperative, identify a shared economic need, assemble committed prospective members, test whether the venture can support itself, choose a suitable legal structure, agree on governance and financing, and complete the required filings before operating.
Prove that members can solve a real problem together before spending money on incorporation.
A worker-owned service firm, a neighborhood grocery, and a housing cooperative need different plans even though all use member ownership.
There is no reliable universal startup-cost range. Legal and filing expenses matter, but property, equipment, payroll, member capital, and cash reserves can dominate the budget.
State formation rules and any industry licenses are the main permission gates.
The larger danger is a cooperative with enthusiastic voters but too few people willing to manage the work, fund obligations, and resolve disagreements.
Last fact-checked: October 12, 2026
This guide is for first-time US founders considering worker, consumer, producer, purchasing, or housing cooperatives, as well as employees exploring a business conversion. It covers structure, formation, voting, member investment, taxes, ongoing obligations, and practical launch decisions. Specific filing and tax treatment must be confirmed for the state and activity involved.
1. What a cooperative is and how member ownership works
A cooperative is an enterprise owned and controlled by members who use or participate in it.
Those members may be workers, customers, producers, residents, or a combination of groups, and the benefits of ownership should reflect the cooperative’s purpose.
| Cooperative type | Who the members are | Main operating challenge |
|---|---|---|
| Worker cooperative | People who work in the business | Paying wages, assigning authority, and recognizing different labor contributions |
| Consumer or food cooperative | People who buy goods or services | Recruiting enough purchasing members and running a viable retail or service operation |
| Producer or purchasing cooperative | Businesses or producers pooling activity | Securing dependable volume, suppliers, and member participation |
| Housing cooperative | Residents with ownership rights in a housing organization | Buying property, obtaining financing, and handling resident entry and departure |
| Multi-stakeholder cooperative | More than one member group, such as workers and customers | Balancing groups with different economic interests and decision rights |
Member ownership usually comes with voting and economic rights, but it does not mean every member manages every decision.
A board can set policy and appoint managers for daily operations.
Voting rights, membership classes, and the distribution of benefits must follow the chosen structure’s governing documents and applicable law.
Nor is cooperative ownership a substitute for a workable product or service.
Customers still have alternatives, employees still need to be paid, and lenders still expect repayment.
2. Cooperative corporations and LLCs compared
In the United States, cooperative ownership can be organized through different legal forms.
A state cooperative corporation is one possibility, while a limited liability company (LLC) with a cooperative operating agreement may fit some groups; neither choice should be assumed available on identical terms everywhere.
| Structure | Liability position | Tax treatment | Governance and ownership | Cost and complexity |
|---|---|---|---|---|
| Cooperative corporation | Members generally receive a liability shield, subject to legal exceptions | Cooperative-specific tax rules may apply when requirements are met | State statute, articles, bylaws, directors, and membership rules | State filing plus ongoing corporate and cooperative administration |
| LLC with cooperative provisions | Members generally receive limited liability, subject to exceptions | Depends on federal tax classification and any elections | Operating agreement defines member rights within state law | LLC filings plus detailed custom governance drafting |
| Conventional LLC or corporation | Liability protection depends on the entity and circumstances | Depends on entity type and elections | Can concentrate voting and financial returns among founders or investors | May be simpler when democratic member ownership is unnecessary |
An LLC is not a federal prerequisite to starting a cooperative.
Likewise, adding the word “cooperative” to a company name does not establish member rights, tax status, or compliance with cooperative law.
The legal structure determines which documents control the organization, what filings it makes, how ownership interests can change, and which tax rules require attention.
Ask a cooperative-experienced attorney and accountant to review the intended ownership arrangement before the founders file or promise members particular tax benefits.
3. Who should form a cooperative and what to prove first
Shared values make a promising introduction, but cooperative founders need evidence of shared economic benefit and reliable participation.
Before selecting the entity, establish whether the proposed members have both a reason to join and the ability to keep the venture operating.
A cooperative is a strong fit when members need something they can obtain more effectively together, such as stable employment, a local store, shared purchasing, or long-term housing.
It is a weaker fit when prospective members mainly want a label, cannot agree on responsibilities, or expect a founder to do the work indefinitely.
A small organizing group should carry out this verification sequence:
- Describe the need. Identify the members, the specific economic problem, and the improvement they would receive.
- Confirm actual commitment. Ask each prospective member what work, money, business volume, or other resources they can realistically contribute.
- Test demand. For a worker co-op, seek customers and priced work. For a food co-op, assess shoppers and suppliers. For housing, investigate suitable property and lender requirements.
- Compare alternatives. Decide whether a conventional business, purchasing arrangement, or existing organization could solve the problem with less complexity.
- Test the working relationship. Assign a small task with a deadline and see whether the group delivers, communicates, and handles disagreement.
One founder may be organizing suppliers while others attend meetings and vote on priorities.
If nobody else can take responsibility for the orders, the group has an accountability problem long before it has a legal problem.
Write down roles and time commitments rather than interpreting meeting attendance as operating capacity.
4. Steps to form a cooperative in the United States
The practical formation sequence begins with a credible member group and a feasible plan, then proceeds to structure selection, governance documents, registration, and operational readiness.
The exact state paperwork differs, and property or regulated activities can add approvals.
- Choose the cooperative type and founding group. Record who will own the venture, who will use it, and which members intend to participate at launch.
- Complete a feasibility and funding plan. Estimate demand, operating costs, initial purchases, member investments, borrowing needs, and reserves before making binding commitments.
- Select a lawful entity form. Examine the state cooperative statute and alternative entity rules through the state filing office, then decide how membership and control will be represented.
- Agree on preliminary governance and capital terms. Set the intended voting system, board authority, member admission, compensation principles, and rules for leaving.
- Prepare and submit state formation documents. File the appropriate articles of incorporation or organization and meet the state’s registered-agent requirements when applicable.
- Adopt the governing documents and appoint leadership. Approve bylaws or an operating agreement, document member decisions, and designate directors, officers, or managers as appropriate.
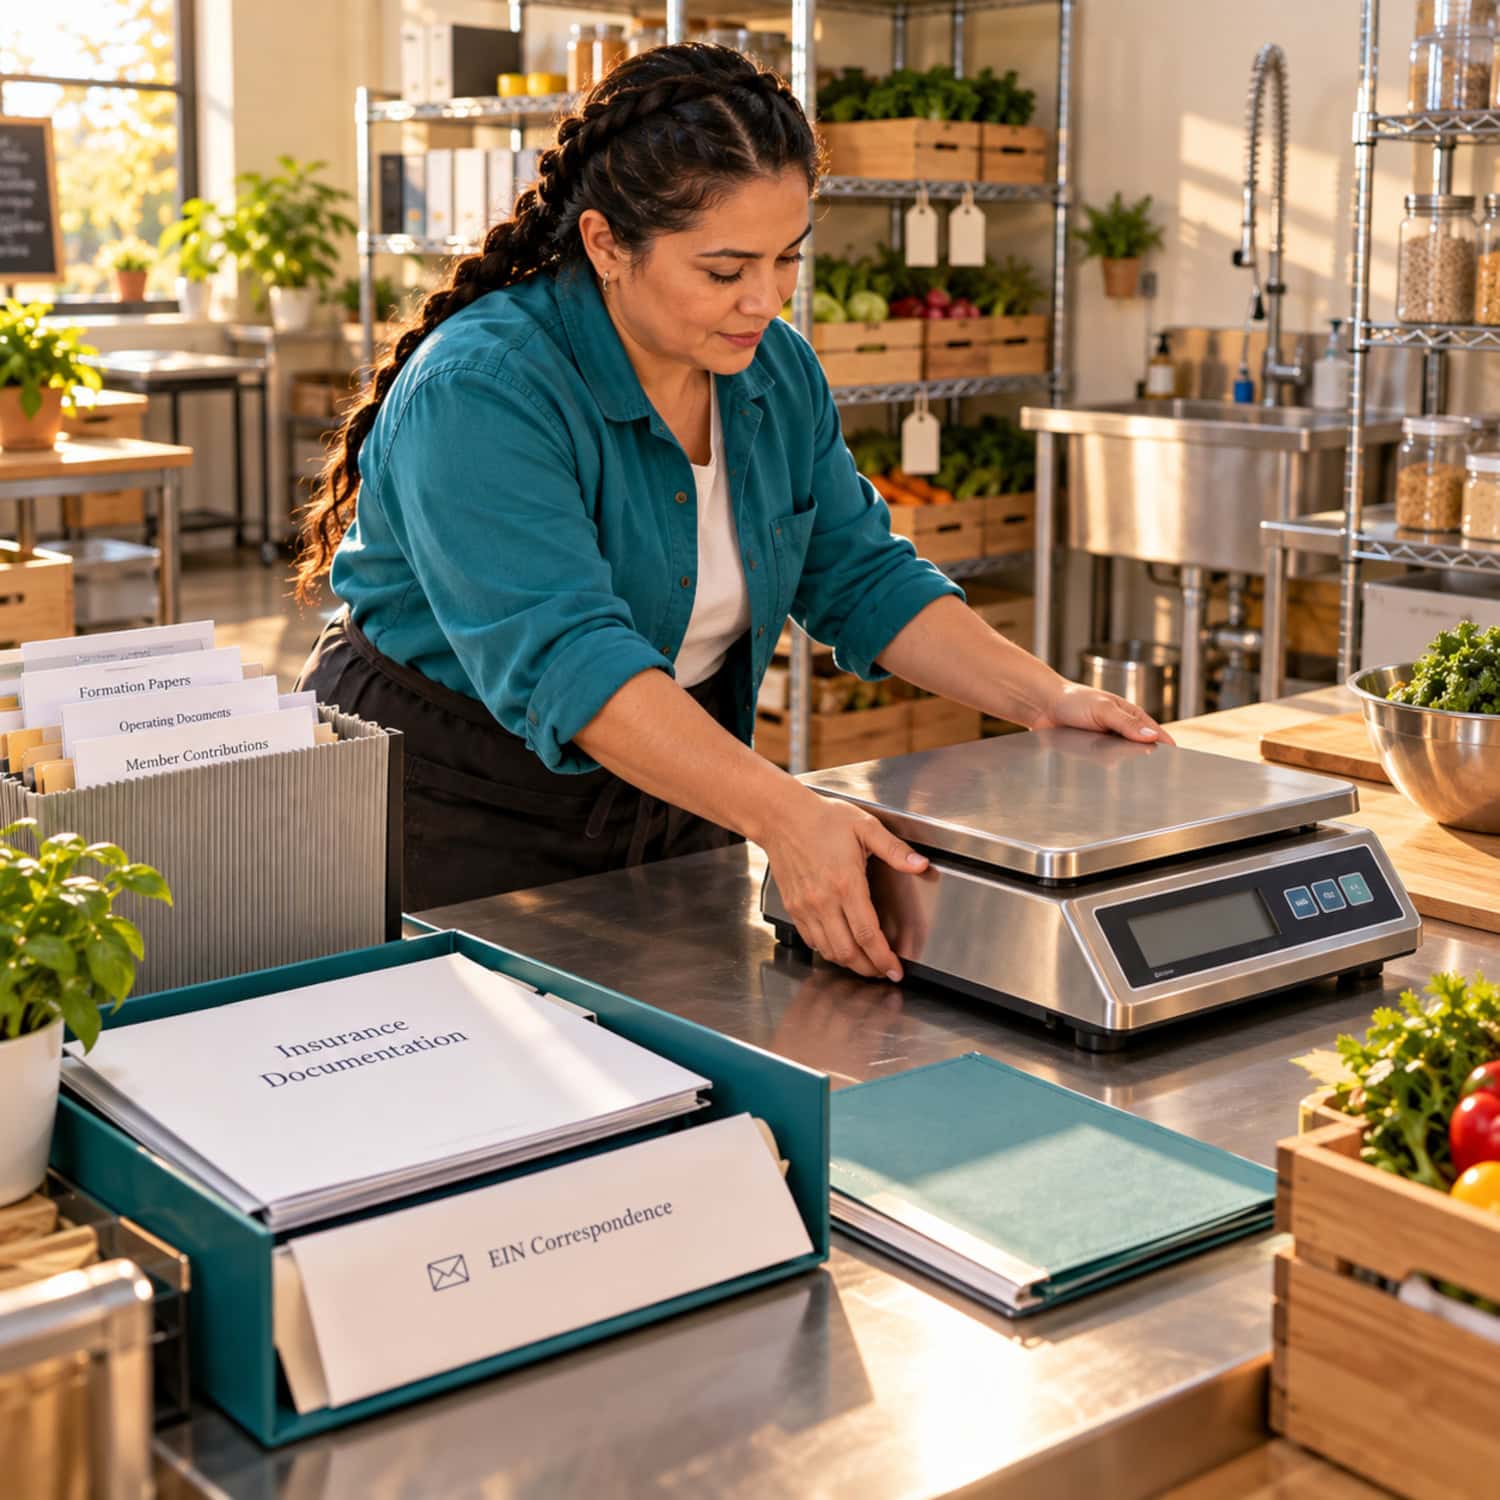
- Obtain a federal employer identification number (EIN). Use the Internal Revenue Service process, then set up banking, accounting, and the proper handling of member contributions.
- Secure operational permissions and protection. Confirm local business licenses, sector permits, insurance, employment obligations, and any property-related approvals before opening or hiring.
- Fund and launch the actual operation. Finalize contracts, establish financial controls, begin delivering the member benefit, and schedule reviews of business performance and governance.
State formation approval alone does not authorize every activity.
A food cooperative operating a grocery may face retail, food-safety, and local premises requirements.
A housing cooperative must address property and lender conditions, while an employer must comply with labor and payroll obligations.
5. Bylaws and agreements that prevent governance breakdowns
Cooperative bylaws or an LLC operating agreement should make ownership, voting, management, and member departures predictable before disagreements arise.
The hardest issues are often practical: one member brings more cash, another works more hours, and a third needs to leave when the business has little money available.
At a minimum, the governing documents and related membership agreements should address:
- Admission and contributions: who qualifies, whether there is a buy-in, and how members with limited cash participate.
- Voting and representation: who votes, whether different member classes exist, and which decisions need member approval.
- Board and management authority: which matters the members reserve and which decisions managers can make promptly.
- Pay and economic benefits: how wages, founder contributions, retained earnings, and member distributions are treated separately.
- Conflict and accountability: how complaints, nonperformance, deadlocks, and removal are handled fairly.
- Member departure: how ownership interests are valued, transferred, or redeemed and whether repayments can be delayed to protect cash.
A one-member-one-vote approach is common, but it does not require unanimity on routine purchases.
A group that votes on every supplier invoice can exhaust its members without improving accountability.
Establish the decisions members truly need to control and delegate the rest under transparent reporting rules.
Questions to settle before signing member agreements
- Who has authority when a delivery fails or an urgent customer issue arises?
- What happens if a founding member stops contributing the agreed hours or capital?
- How are unequal founder loans or investments recorded without silently increasing voting power?
- What can a departing member claim, and when can the cooperative afford to pay it?
- How will the group resolve a closely divided vote that affects members’ livelihoods?
Consider a departing worker-owner who asks for immediate repayment in the same month that payroll and supplier bills are due.
A generous redemption promise on paper can create a cash emergency. Document the valuation method and timing before anyone joins.
6. Cooperative taxation and worker compensation
A cooperative’s ownership system does not by itself settle its federal tax classification or payroll obligations.
The entity’s form, activities, member relationships, and tax elections affect the treatment of business income and member payments.
For a cooperative corporation, patronage allocations or refunds are potential mechanisms for returning eligible earnings according to members’ participation.
They should not be confused with regular wages, investment returns, or an automatic tax exemption.
Some cooperative tax provisions apply only when particular requirements are satisfied.
Worker-members may still have employment and payroll obligations, including wage and worker-classification rules.
State and local labor requirements vary, so the relevant labor agency and revenue authorities should be checked before deciding how owners will be paid.
Ownership alone does not make every payment a distribution rather than compensation.
Separate the records for labor pay, member capital accounts, cooperative earnings, and distributions.
That distinction becomes particularly important when the group hires nonmember employees or introduces new members after founders have made unequal contributions.
7. Ongoing filings and operating compliance
A registered cooperative must maintain its entity status and satisfy the rules attached to its actual business.
The state of formation, tax classification, workforce, and industry determine the recurring work.
| Obligation | When it matters | Where to confirm |
|---|---|---|
| State reports and registered-agent information | At formation and on the state’s required schedule | State filing office |
| Federal tax returns and any elections | Each applicable tax period or election event | Internal Revenue Service and a qualified tax professional |
| State and local tax accounts | When the cooperative has taxable sales, payroll, or other reportable activity | State revenue department and local tax office |
| Payroll and worker protections | When people work for the cooperative | Federal and state labor agencies |
| Industry and premises permits | Before and during regulated operations, with renewals as required | Local licensing, health, zoning, or other relevant regulators |
| Governance records | After required meetings, votes, member changes, and board decisions | Governing documents and applicable state law |
| Insurance coverage | Before taking on the risks the policy must cover and during operations | Licensed insurance agent and applicable state insurance requirements |
General liability insurance, property coverage, directors’ and officers’ protection, and workers’ compensation may matter in different settings.
A housing cooperative and a small consulting cooperative should not buy identical policies by habit.
Insure the real assets, people, and activities involved.
Limited liability is useful but not absolute.
Personal guarantees, individual misconduct, and failures to respect entity obligations can still expose members or managers to risk.
8. Cooperative startup costs and ways to fund the business
Cooperative startup costs are driven mainly by the enterprise being built, not by its ownership label.
A service cooperative may need little equipment, while a grocery needs premises and stock and a housing cooperative faces property acquisition and lender requirements.
| Cost category | What changes the amount | Why it matters before formation |
|---|---|---|
| Formation and professional work | State filing, customized agreements, legal and accounting review | Complex membership rights cost more to design and administer |
| Member capital | Buy-ins, initial shares, or agreed member loans | Large contributions can exclude intended members |
| Operating setup | Property, inventory, equipment, software, and insurance | The business format determines how much cash is tied up before sales |
| Payroll and overhead | Paid staff, occupancy costs, and supplier terms | Expenses continue even when sales are weak |
| Cash reserve | Debt payments, member exits, and slow collections | A cooperative needs liquidity after opening, not just on filing day |
Capital may come from member contributions, member loans, outside loans, or suitable development support.
Funding that gives investors control must be evaluated against the intended member voting rights.
Grant possibilities are not a substitute for a plan that can support ongoing expenses.
An illustrative operating cash test
Operating cash before debt payments, taxes, and member distributions equals sales minus variable costs, payroll, and fixed overhead.
The following figures are illustrative numbers, not startup-cost or profitability benchmarks.
| Monthly item | Planned sales | Sales at half the plan |
|---|---|---|
| Customer revenue | $20,000 | $10,000 |
| Variable operating costs | $8,000 | $4,000 |
| Payroll | $7,000 | $7,000 |
| Fixed overhead | $4,000 | $4,000 |
| Cash before financing and taxes | $1,000 | -$5,000 |
The planned month produces only $1,000 before any loan payment or member distribution.
At half the revenue, variable costs fall but payroll and overhead remain, producing a $5,000 shortfall.
A founding group expecting to return member investments quickly would need to reconsider that promise or increase its reserve.
Do not count a membership payment as recurring customer revenue unless it actually represents revenue under the cooperative’s accounting treatment.
Likewise, a worker’s unpaid startup labor does not prove the enterprise can afford that position after launch.
9. Common cooperative myths and costly mistakes
Cooperatives often run into trouble when democratic ownership is expected to solve business problems automatically.
The more consequential failures involve unclear work assignments, insufficient cash, unmanaged conflict, and unrealistic promises about member exits.
| Myth | What actually happens |
|---|---|
| Every member should approve every operational decision | Member governance can coexist with delegated managers, budgets, and defined board oversight. |
| Equal votes require equal wages or capital contributions | Voting, compensation, and member investment serve different purposes and need separate rules. |
| Incorporation makes the cooperative financially viable | Customers, members, operating capacity, and cash flow still determine survival. |
| A cooperative cannot have nonmember employees | Employee ownership and employment status are different questions; the governing model and applicable law control the arrangement. |
| Members always get their investment back when they leave | Redemption rights depend on the agreements, the law, and the cooperative’s ability to pay. |
| Conventional outside funding is the only way to grow | Member capital and suitable debt may work, but their affordability and repayment terms need testing. |
Beware of formation packages that emphasize a template filing while leaving membership terms, financing, and decision authority unresolved.
The documents are useful only when they describe a workable organization.
10. Converting an existing business into a cooperative
Buying or converting an existing business introduces a different set of decisions from founding a cooperative from scratch.
Workers must evaluate the purchase price, financing, management transition, and how employees who do not want ownership will be treated.
A conventional owner may wish to sell to employees, or a business already structured as an LLC may want to admit worker-owners.
Neither path requires pretending every current worker wants the same responsibilities or can make the same investment.
Conversion due diligence
- Examine the business finances. Review financial statements, debts, customer dependence, contracts, payroll, and equipment obligations.
- Identify participating and nonparticipating workers. Establish who wants membership, the entry terms, and fair working arrangements for others.
- Determine the transaction structure. Assess whether the cooperative will buy business assets, acquire ownership interests, or use another legally suitable conversion route.
- Price and finance the acquisition. Test repayment against realistic operating cash rather than optimistic growth or unpaid owner labor.
- Set the transition plan. Document management responsibilities, training, member voting, founder or seller payments, and member exit rights.
- Confirm approvals and contracts. Review lender requirements, transfer restrictions, state filings, licenses, and existing agreements before closing.
Where the original owner wants to stay involved, put the transition of power and compensation in writing.
A worker buyout that leaves all decisions with the seller may disappoint the employees who expected meaningful control.
FAQ
How many people do you need to start a cooperative?
It depends on the state, legal form, and cooperative type, because membership minimums and eligibility rules vary.
Confirm the applicable requirements with the state filing office before registering. See Section 4.
Can you start a cooperative with very little money?
Yes, some service cooperatives can begin with relatively modest equipment needs, but they still require enough money to meet actual operating obligations.
Property-intensive models face different financing demands. See Section 8.
Do all cooperative members get the same pay?
No, equal voting rights do not automatically require equal wages or identical returns on invested capital.
The compensation and distribution rules must be lawful and agreed upon in advance. See Sections 5 and 6.
Does a cooperative need an LLC?
No, a cooperative may use a cooperative corporation or another suitable entity, subject to state law.
The choice changes governance documents and tax questions. See Section 2.
Can a worker cooperative hire people who are not members?
Yes, nonmember employment is possible in cooperative businesses, subject to the chosen structure and applicable labor rules.
Membership eligibility and admission terms should be stated in the governing documents. See Sections 5 and 6.
How long does it take to start a cooperative?
It depends on member readiness, financing, filings, and the operating activity, with housing and property-dependent projects often requiring additional work.
State processing time alone cannot predict the launch date. See Sections 4 and 8.
Conclusion
Build the member group and operating case before building the legal shell.
The cooperative structure can protect democratic participation, but members must still deliver the service, manage money, and take responsibility for decisions.
- Confirm the shared need: Test real member commitment and demand before agreeing to invest.
- Set the ownership rules: Document voting, management, compensation, capital, and exit terms before filing and signing commitments.
- Fund the operation realistically: Check regulatory permissions and stress-test cash needs before launch.
Further reading
- USDA Rural Development – How to Start a Cooperative: A federal cooperative development manual covering feasibility, capitalization, organizing, and formation stages.
- U.S. Co-ops – Co-op 101: An introduction to cooperative ownership and the organizing decisions involved in launching a member-owned business.
- University of Nebraska – Starting a Cooperative: A cooperative development checklist for evaluating the founding group’s readiness and practical startup requirements.
- U.S. Federation of Worker Cooperatives – Startup Workplaces: Worker-cooperative resources on membership fees, governance, financing, and conflict resolution.
- Cooperative Development Institute – Co-op Start-Up Guide: A specialist startup packet covering organizing, cooperative bylaws, and building an effective founding committee.